Local Knowledge • Coastal Expertise
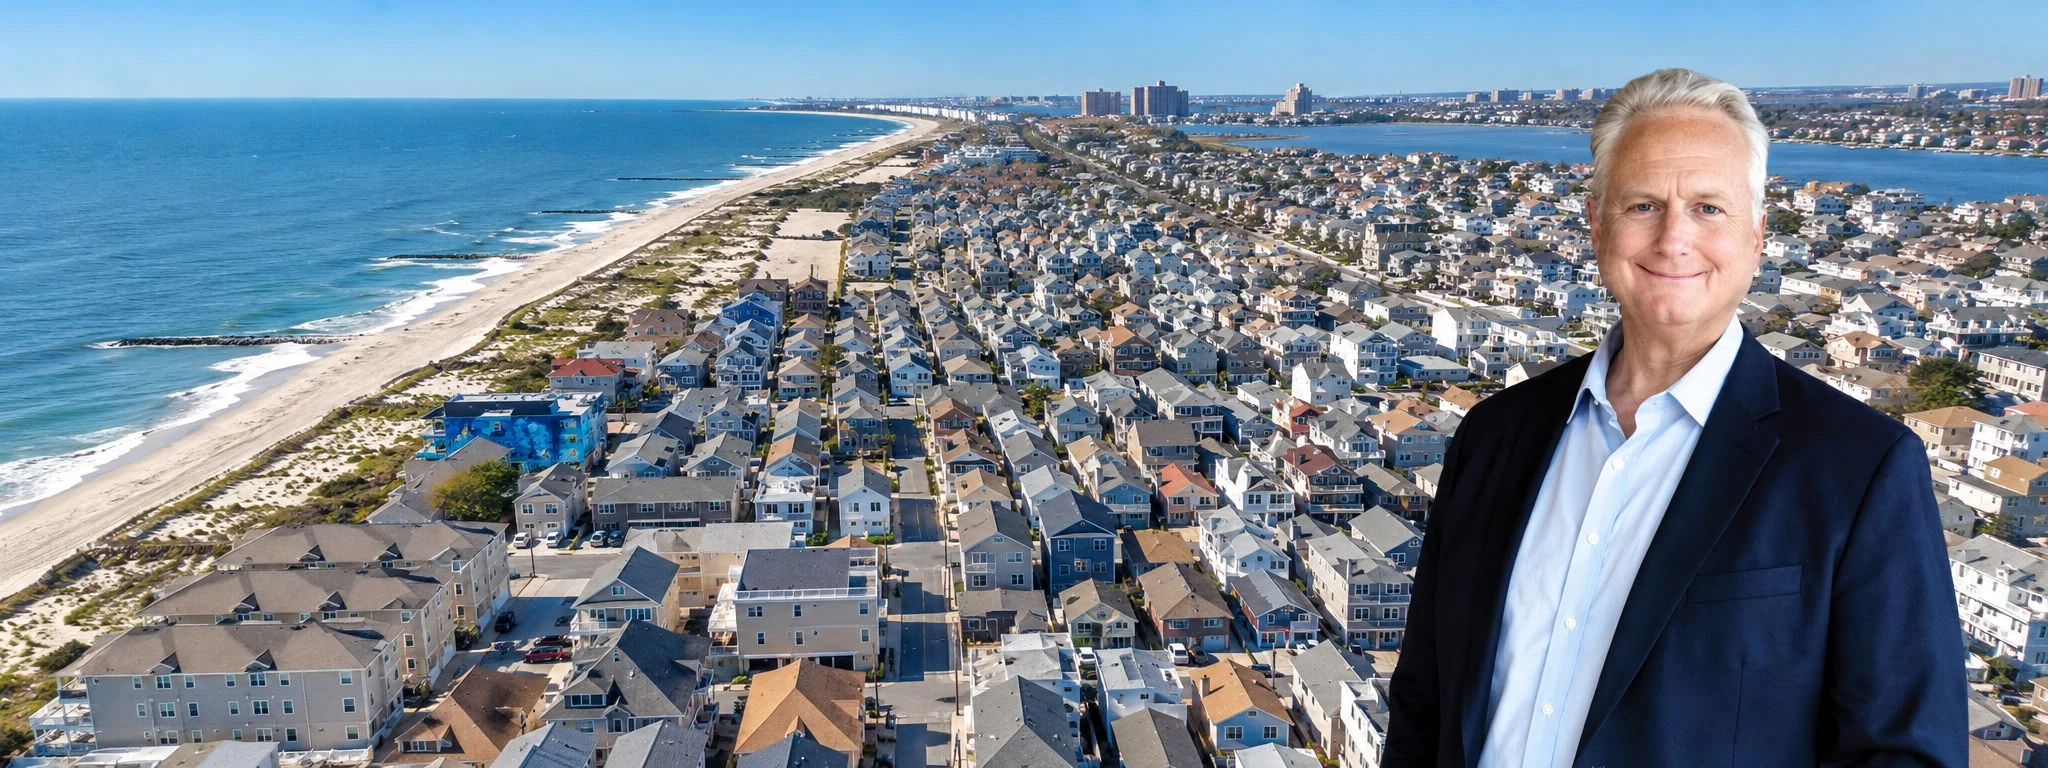
Long Island homes can be complicated to insure, especially near the water. Wind, flood exposure, roof condition, replacement cost, construction and changing underwriting requirements can all affect your options. I've spent more than 40 years helping New York homeowners understand those issues and find coverage that fits the property and the family behind it.
- 40+ Years Experience
- CPCU Designation
- Family Legacy Since 1936
- Licensed Nationwide
From the North Shore to the South Shore and the East End, I understand the insurance issues that come with owning a home on Long Island, particularly near the water.
Long Island Insurance Requires Local Knowledge
A Long Island home shouldn’t be evaluated simply by its ZIP code. I look at the property itself, including its location, roof, construction, estimated rebuilding cost and claims history, alongside the coverage and markets that may be available.
Coastal Exposure
How close the home is to the coast and the type of wind and weather exposure it faces.
Proximity to Water
Canals, bays, Sound, and ocean exposure specific to Nassau and Suffolk shores.
Flood Considerations
Flood zone, elevation and whether separate flood coverage should be considered.
Wind Exposure
Wind and hurricane deductibles and other policy provisions that can affect a coastal home.
Roof Age & Condition
Roof age, condition and construction, all of which can affect underwriting.
Replacement Cost
The estimated cost to rebuild the home, including local labor and material costs.
Prior Claims History
Prior claims can affect eligibility and pricing, so I look at the history and how it may affect your options.
Available Insurance Markets
Access through Acrisure to a broad range of standard and specialty insurance markets.
Michael Hastava, CPCU
Insurance Advisor
Coastal Insurance Isn’t Just a Specialty. It’s Personal.
I grew up in a coastal community, so the risks that come with living near the water have always been personal to me.
Experience Matters. So Does Showing Up.
That became especially personal during Superstorm Sandy. Our own office and homes were severely damaged, just as they were for many of our clients and neighbors. While dealing with our own damage, I also handled many hundreds of claims for clients whose homes and lives had been disrupted by the storm.
That experience taught me things no textbook or online quoting system can. You learn very quickly which details in a policy matter when a major loss actually happens. It’s one of the reasons I spend so much time understanding the property and the coverage before there’s a claim.
“My clients matter to me.”
— Michael Hastava, CPCU
Experience matters most when you actually need your insurance.
Homeowners Insurance and Flood Insurance Are Different.
Standard homeowners insurance generally does not cover flood damage. Separate flood insurance may be appropriate or required. Coverage, exclusions, deductibles and limits vary by policy. I’ll help you look at the two policies together.
Standard Homeowners Policy
A homeowners policy covers insured risks according to its terms, but it generally does not cover flood.
Dedicated Flood Insurance
Flood insurance is separate from a standard homeowners policy and may be available through the NFIP or private flood insurers.
Moving Off Long Island? Your Insurance Advisor Doesn’t Have to Stay Behind.
Many of my Long Island clients move south, buy a second home or retire in Florida or the Carolinas. I’m licensed nationwide, so I can often continue advising them. A move may mean changing policies or insurance companies, but it doesn’t necessarily mean starting over with someone new.
Advice When You Move
Long Island → Florida
Second homes, retirement & homeowners insurance
Long Island → North Carolina
Helping clients who relocate or purchase a second home.
Long Island → South Carolina
Helping clients who relocate or purchase a second home.
Long Island → Anywhere in the U.S.
Licensed nationwide across all 50 states
Personal Advice. National Resources.
You’ll work with me directly, with access to the resources and insurance markets available through Acrisure. I’ll explain the options and help you understand the differences that matter for your property.
Good advice should come before the sale.
Send me your current policy for a second opinion. If I think it makes sense to keep it, I’ll say so. If I see something worth considering, I’ll explain why.
Confidential review • No obligation • Direct personal response from Mike